 How-to
How Do You Calculate DSCR for Rental Properties?
Last Updated: November 4, 2026
Quick Summary
To calculate DSCR, divide net operating income by annual debt service. Subtract vacancy and operating expenses from gross rent to get NOI, then multiply the monthly PITIA payment by twelve for debt service. A ratio of 1.25 or higher is generally considered good.
- NOI is gross rent minus a vacancy allowance and operating expenses, calculated before debt.
- Annual debt service is the monthly PITIA payment multiplied by twelve.
- A DSCR below 1.0 means the property loses money each month.
- Loan size and rent move the ratio by tenths, while a 100-basis-point rate move shifts it only a few hundredths.
- Lenders may apply a market management fee even if you self-manage the property.
Table of Contents
- What Is DSCR and Why Lenders Ask For It
- The DSCR Formula: Net Operating Income Divided by Debt Service
- Step-by-Step: How to Calculate DSCR for Rental Properties
- What Is a Good DSCR Ratio for a Rental Property?
- DSCR Loan Requirements Lenders Actually Check
- Rental Property Cash Flow Analysis Beyond the Ratio
- Adjustments Competitors Skip: Taxes, Short-Term Rentals, HOA Dues and Management Fees
- Run Your Numbers Before You Apply for DSCR Financing
- Frequently Asked Questions
What Is DSCR and Why Lenders Ask For It
DSCR stands for debt service coverage ratio.
Lenders ask for DSCR because it replaces income verification. Instead of relying on personal income documentation, lenders can check the property.
The math is simple. If a property collects more rent than its total payment, the ratio lands above 1.0.
That is why the ratio drives loan size, rate, and terms at once.
The DSCR Formula: Net Operating Income Divided by Debt Service
The DSCR formula is net operating income divided by annual debt service. That is the whole equation. Everything else in this guide is about getting those two numbers right.
Here is the structure:
- Net operating income (NOI): the rent the property collects minus its operating expenses
- Annual debt service: the full yearly payment on the loan, including principal, interest, taxes, and insurance
- DSCR: NOI divided by annual debt service
The formula is simple, but what counts inside each number is where many files get stuck.
Calculating NOI From Gross Rental Income
Start with gross rental income, the total rent the property brings in over a year. Subtract a vacancy allowance, because no unit stays full forever, a common approach is a few weeks of rent as a cushion.
Next, subtract the operating expenses. These are the costs of running the property:
- Property taxes
- Insurance
- Repairs and maintenance
Do not subtract the mortgage payment here. NOI measures the property before debt. Mixing the two is the most common error we see on self-prepared files.
Calculating Annual Debt Service From PITIA
Annual debt service is the PITIA payment multiplied by twelve. PITIA stands for principal, interest, taxes, and insurance.
Principal and interest come from the loan amount, rate, and amortization schedule; a lender can run that in seconds.
One detail most borrowers miss: the taxes and insurance inside PITIA are the same dollars you already subtracted from NOI. That is correct.
Step-by-Step: How to Calculate DSCR for Rental Properties
Work these steps in order to arrive at a DSCR figure you can document for any lender.
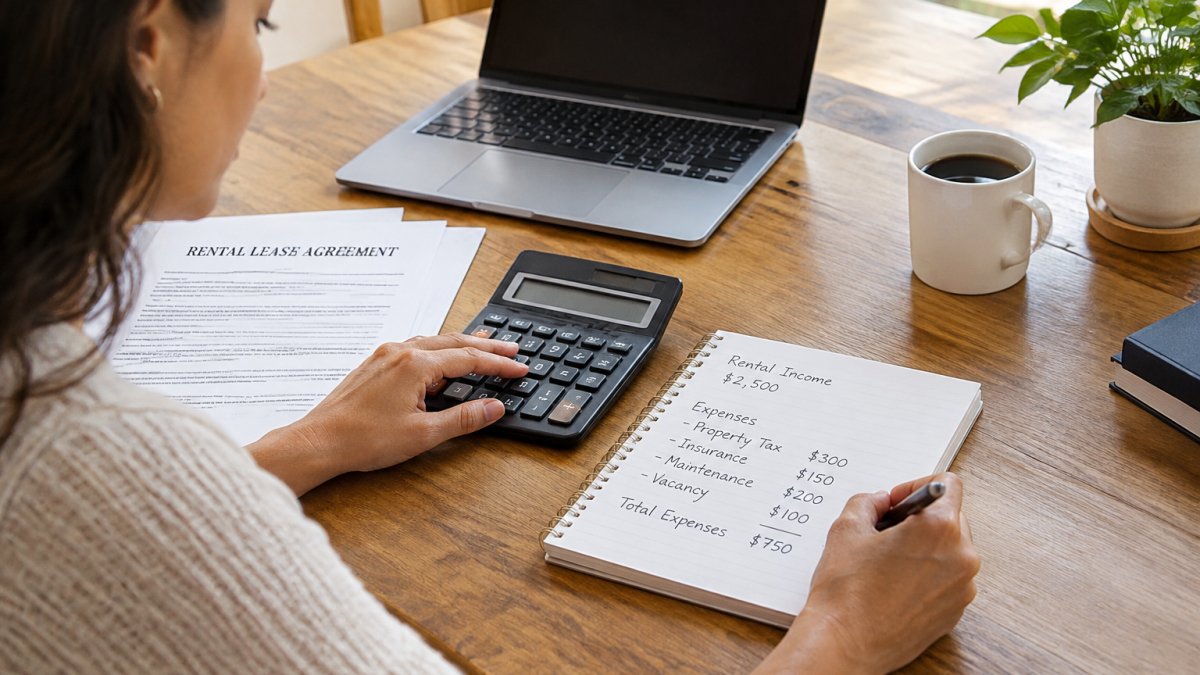
- Add up annual gross rental income. Use the signed lease or market rent, whichever the lender accepts.
- Apply a vacancy allowance. Subtract a realistic cushion for turnover and empty months.
- List every operating expense. Taxes, insurance, repairs, management, HOA dues, owner-paid utilities.
- Subtract expenses from income. The result is your NOI.
- Calculate the monthly PITIA payment. Principal, interest, taxes, insurance, plus HOA dues.
- Multiply PITIA by twelve. That gives you annual debt service.
- Divide NOI by annual debt service. The result is your DSCR.
Run the numbers twice: once with the rent you expect and once with the rent you can prove. Lenders underwrite the second one.
A Fully Worked Example
Numbers make the process click. Take a single-family rental with a signed twelve-month lease at $2,400 per month.
Step 1, Gross rental income. $2,400 × 12 = $28,800 per year.
Step 2, Vacancy allowance. A common underwriting approach is 5% of gross rent, or roughly two and a half weeks. 5% × $28,800 = $1,440. Effective gross income is $27,360.
Step 3, Operating expenses. Using typical figures for this property class:
- Property taxes: $3,600 per year
- Landlord insurance: $1,800 per year
- Repairs and maintenance allowance: $1,440 per year (5% of gross rent)
Total operating expenses: $9,000.
Step 4, NOI. $27,360 − $9,000 = $18,360.
Step 6, Annual debt service. $2,496 × 12 = $29,952.
Step 7, DSCR. $18,360 ÷ $29,952 = 0.61.
That result tells you the property does not cover its debt at this loan size. The fix is typically a smaller loan, more rent, or a lower rate.
Watch out: the vacancy allowance and repair reserve are the two lines most self-prepared files understate. Lenders apply their own minimums, and a file that looks like 1.25 on your spreadsheet can land at 1.10 in underwriting once those cushions are reset.
What-If Modeling: How Rate and Vacancy Move the Ratio
The ratio is sensitive to a handful of inputs. Using the same $18,360 NOI and a $300,000 loan, here is how DSCR shifts as the interest rate and vacancy assumption change (illustrative figures):
| Scenario | Rate | Vacancy | Approx. PITIA | Annual Debt Service | DSCR |
|---|---|---|---|---|---|
| Base case | 7.25% | 5% | $2,496 | $29,952 | 0.61 |
| Rate drops 100 bps | 6.25% | 5% | $2,347 | $28,164 | 0.65 |
| Rate rises 100 bps | 8.25% | 5% | $2,650 | $31,800 | 0.58 |
| Vacancy doubles | 7.25% | 10% | $2,496 | $29,952 | 0.58 |
| Smaller loan | 7.25% | 5% | $1,664 | $19,968 | 0.92 |
The takeaway is mechanical: a 100-basis-point rate move shifts DSCR by a few hundredths, while loan size and rent move it by tenths. If your ratio is borderline, the lever with the most leverage is the loan amount, not the rate quote.
Short-Term vs. Long-Term Rental Income
A twelve-month lease gives underwriting a stable number to divide. Short-term rental income does not. Platforms like Airbnb and VRBO produce seasonal, variable revenue, and most lenders respond by applying a higher vacancy factor or using a trailing twelve-month average rather than a peak-season projection. Our guide on using DSCR loans to purchase short term rentals covers how the income is treated in detail.
What Is a Good DSCR Ratio for a Rental Property?
A good DSCR ratio for a rental property is generally 1.25 or higher. At that level, the property earns a quarter more than it owes each year, which gives the lender a cushion for vacancies and repairs.
A ratio of 1.0 is break-even. The rent covers the payment and nothing more. Many lenders treat 1.0 as the absolute floor, and some will approve below it with compensating factors like strong reserves or a lower loan-to-value ratio.
Here is how to read your result:
- Below 1.0: the property loses money each month. Expect a decline or a smaller loan.
- 1.0 to 1.20: workable, but tight. Expect closer scrutiny of expenses.
- 1.25 and above: the sweet spot for most rental loan programs.
Why the Floor Is Not the Same at Every Lender
The ratio bands above are a starting point, not a rule. Underwriting guidelines vary by lender, and the ratio is one input among several. A lender will often accept a lower ratio when other risk factors are strong, and demand a higher one when they are not. The variables that move the floor:
- Loan-to-value. A lower LTV means more equity in the deal, which gives the lender a bigger cushion if the property has to be sold. Many programs will stretch on ratio when LTV is at or below 65% to 70%.
- Reserves. Cash left after closing is a direct offset to a thin ratio. Reserve requirements vary by lender and by how strong the rest of the file is.
- Credit score. Credit score requirements and pricing vary by lender.
The Ratio Is a Negotiation, Not a Pass-Fail
In practice, DSCR functions more like a dial than a simple pass-or-fail threshold.
That is why running the calculation before you apply matters.
Watch out: a lender's published minimum may not be the number your file is underwritten against. Lender-specific overlays can raise the effective floor, so review the term sheet carefully.
If your number lands under the floor, do not guess at fixes. Read our breakdown of the minimum DSCR ratio for investment property approval to see exactly where lenders set the line and why.
DSCR Loan Requirements Lenders Actually Check
DSCR loan requirements go beyond the ratio itself. The ratio is the headline, but underwriting checks several supporting items before a file clears.
Expect lenders to review:
- The property's income. A lease or a rent schedule, and sometimes a market rent analysis.
- The full expense picture. Taxes, insurance, HOA dues, and a repair allowance.
- Credit and reserves. Many programs are lenient on credit, but reserves still matter.
Notice what is missing: personal income documentation. That is the point of this loan.
First-time investors should work through the full checklist before applying. Our guide to DSCR loan requirements for first time investors covers each item in detail.
Rental Property Cash Flow Analysis Beyond the Ratio
Rental property cash flow analysis is where the ratio stops being enough. DSCR tells you the property covers its debt.
Cash flow is what is left after everything is paid. That means the mortgage, yes, but also the costs the ratio quietly ignores:
- Capital expenditures. Roofs, HVAC systems, and water heaters do not last forever. Set aside money every month for the year they fail.
- Turnover costs. Painting, cleaning, and lost rent between tenants.
- Higher vacancy than the allowance. A soft market can push empty months past your cushion.
A property can pass at 1.25 and still drain your bank account if capital reserves are thin.
The fix is simple. Build a real reserve line into your cash flow model, not just the lender's minimum. If the deal still works after that, you have a property.
Adjustments Competitors Skip: Taxes, Short-Term Rentals, HOA Dues and Management Fees
Four adjustments separate a real DSCR calculation from a rough estimate. Most quick calculators skip them, and each one can move your ratio enough to change the outcome.
Taxes. Property taxes are reassessed after a sale in many markets. Underwriting may use the new assessed value, not last year's bill.
Short-term rentals. Short-term rental income is seasonal and less predictable than a twelve-month lease.
HOA dues. HOA dues hit twice: they count as an operating expense in NOI and again inside PITIA if the lender includes them.
Management fees. If you self-manage, do not assume a lender will credit you with zero management cost.
These four items are why two investors can run the same property and get different ratios. The property did not change. The assumptions did.
Run Your Numbers Before You Apply for DSCR Financing
Run your own numbers first, then let underwriting confirm them. The investors who close fastest arrive with a clean, defensible calculation and no surprises buried in the file.
Here is the pre-application checklist we recommend:
- Annual gross rental income documented with a lease or rent schedule
- Vacancy allowance applied at a realistic level
- Every operating expense listed, including HOA dues and management fees
If you already own the property and want to move it into better terms, the same math applies. Our walkthrough on refinancing rental properties with DSCR loans shows how to model the new payment against your current one.
Kala Group Capital provides a credit decision in 30 seconds and a preliminary term sheet in as little as 5 minutes. Closings run in as few as 3 days on loans from $500K to $2 Million, through its online platform.
Bring us a property with a ratio that holds up, and we will show you how fast financing can actually move.
Frequently Asked Questions
How do you calculate DSCR for a rental property?
Divide net operating income by annual debt service. Start with gross rental income, subtract vacancy allowance and operating expenses (property taxes, insurance, repairs, management fees, HOA dues) to get NOI. Then add up 12 months of principal, interest, taxes and insurance on the loan to get annual debt service. A property with $36,000 NOI and $30,000 in annual debt service has a DSCR of 1.20. Run the math before you apply so you know which loan amount your rent can support.
What is a good DSCR ratio for a rental property?
Many lenders look for a ratio of 1.20 or higher, meaning the property brings in 20% more income than it owes on the loan. Ratios above 1.25 are often viewed more favorably by lenders. Below 1.0 the property does not cover its own debt from rent, which usually means a denial or a larger down payment requirement. A higher DSCR is generally considered stronger, but a ratio comfortably above 1.25 is often treated as healthy.
Does the DSCR calculation include property taxes and insurance?
Yes. Annual debt service is built from PITIA: principal, interest, taxes and insurance. Property taxes and hazard insurance are part of the monthly payment the lender uses, so they belong in the denominator. They also appear in NOI as operating expenses. Keep the two uses straight: taxes and insurance reduce NOI when you calculate it, and they are also counted inside the debt service figure the lender quotes.
How does vacancy rate affect my DSCR calculation?
Vacancy lowers NOI, so it lowers DSCR. Lenders often apply a vacancy factor to gross rent even if the property is currently occupied; the percentage varies by lender. On $36,000 of gross rent, a 5% vacancy allowance removes $1,800 from income before expenses are subtracted. Short-term rentals may be treated differently because income can vary more. Using the lender's vacancy assumption instead of your own best-case number prevents surprises in underwriting.
The ratio is the easy part. The work is in the assumptions behind it, and that is where most files stall. Kala Group Capital gives you a credit decision in 30 seconds, a preliminary term sheet in under 5 minutes, and closings in as few as 3 days, so your numbers meet underwriting without the wait. Get started with Kala Group Capital and turn your rental analysis into funded capital.



