 ultimate-guide
Real Estate Loan Underwriting Process Explained
Table of Contents
- What Is Real Estate Loan Underwriting?
- How the Underwriting Process Works
- Key Factors Underwriters Review
- Mortgage Underwriting Timeline: What to Expect
- Common Underwriting Red Flags That Delay Approval
- DSCR Loan Underwriting Requirements
- Underwriting for Non-W2 Borrowers and Self-Employed Investors
- Post-Closing Quality Control
Last Updated: August 28, 2026
What Is Real Estate Loan Underwriting?
Real estate loan underwriting is the process a lender uses to evaluate your financial profile, creditworthiness, and property details to decide whether to approve your mortgage application. It's the critical step between submitting your loan application and receiving a clear-to-close status. During underwriting, a trained underwriter examines your income documentation, credit score, debt-to-income ratio, asset verification, and the property appraisal to assess the risk of lending you money.
Underwriting is the lender's due diligence phase. You've been pre-approved based on preliminary information, but now the underwriter verifies everything you claimed on your application and confirms your financial situation supports the loan amount. This process typically takes 5-10 business days, though it can extend longer if issues arise. For experienced real estate investors working with Kala Group Capital, understanding this process is essential. Kala Group Capital's simplified underwriting approach delivers credit decisions in just 30 seconds and preliminary term sheets in under 5 minutes, meaning you spend less time waiting and more time executing your investment strategy.
How the Underwriting Process Works
The loan underwriting process follows a structured path from initial application through clear-to-close approval. Each step has a specific purpose: gathering information, verifying facts, assessing risk, and resolving any issues before funding.
Step 1: Initial Application and Pre-Qualification
Your journey begins when you complete the mortgage application, providing the property address, purchase price, loan amount, employment history, income, assets, and liabilities. The lender's loan processor compiles this into a formal application file.
Pre-qualification happens quickly. A loan officer reviews your application against basic lending criteria and pulls your credit report. Many lenders, including Kala Group Capital, provide pre-qualification decisions within minutes. However, pre-qualification is not a guarantee, it's a preliminary assessment based on limited information. The real evaluation comes during underwriting.
Step 2: Document Submission and Verification
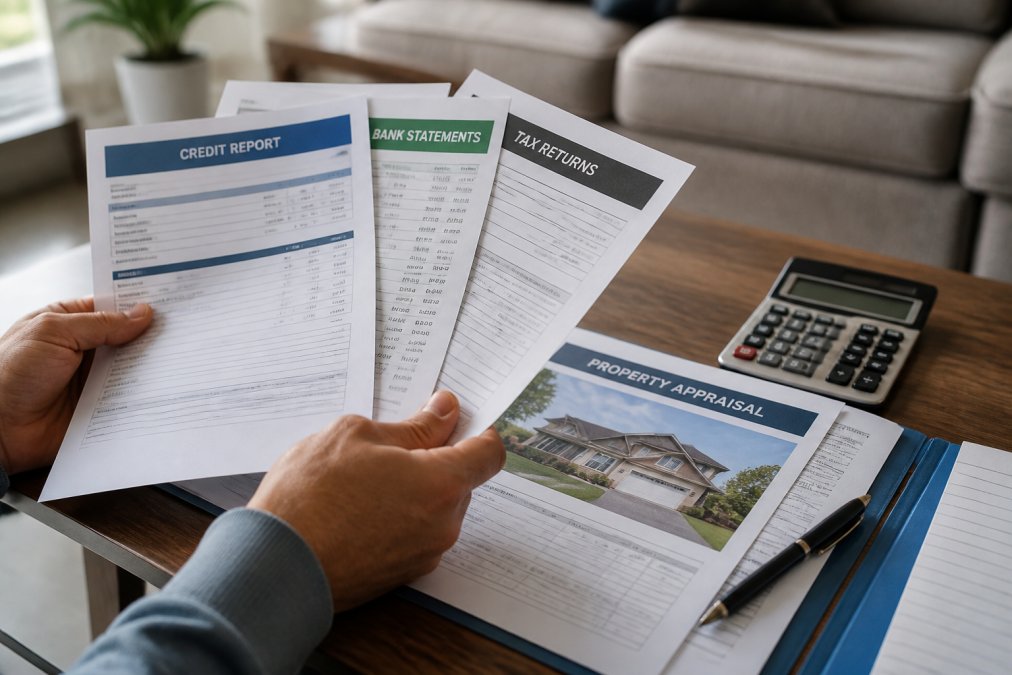
Once pre-qualified, the processor requests documentation to support your application. You'll submit two years of personal tax returns, recent pay stubs, bank statements (usually last two months), proof of employment verification, explanation letters for any credit issues or income gaps, proof of down payment funds, and a list of assets and liabilities.
The underwriter reviews each document, verifies employment by contacting your employer, confirms bank account balances, and checks that your income documentation aligns with your application. Any discrepancies trigger a request for clarification or additional documents.
Step 3: Automated Underwriting Systems vs. Manual Review
Most modern lenders use Automated Underwriting Systems (AUS) to simplify the initial evaluation. An AUS analyzes your financial data against established lending guidelines and produces a preliminary recommendation: approved, suspended, or denied. However, AUS systems follow rigid rules and may flag borderline situations requiring manual review. Many investors appreciate lenders who combine both approaches. Kala Group Capital leverages automated systems for speed while maintaining human underwriter review for complex scenarios, particularly for non-traditional borrowers like self-employed investors or those with non-W2 income structures.
Step 4: The Conditions Phase
After the AUS review and initial underwriter assessment, you typically receive a conditional approval. This means the lender is willing to approve your loan if you satisfy specific conditions. Common conditions include written explanations for late payments, updated bank statements, employer confirmation letters, lien clearance, employment gap documentation, homeowners insurance quotes, or updated appraisals. Borrowers who respond quickly to condition requests move to clear-to-close status faster. For fix-and-flip investors managing multiple projects, responding promptly to conditions is critical to maintaining your timeline.
Step 5: Clear to Close
Once you've satisfied all conditions, the underwriter issues a clear-to-close status. This is your green light, the lender has verified everything, assessed the risk as acceptable, and is ready to fund your loan. Clear-to-close doesn't mean the loan is funded yet; it means underwriting is complete and the loan is ready to move to closing. The title company schedules closing, final walkthrough happens, you sign documents, and funds are disbursed within 2-3 business days.
Key Factors Underwriters Review
Underwriters evaluate your entire financial profile to determine whether you're a creditworthy borrower capable of repaying the loan. They focus on specific metrics that historically predict loan performance.
Credit Score and Financial Profile
Your credit score reflects your payment history, amounts owed, length of credit history, credit mix, and new credit inquiries. Most lenders require a minimum credit score between 620 and 680 for conventional mortgages, though investment property loans often require higher scores (700+).
Beyond the score, underwriters review your credit report line by line, looking for late payments, collections, or charge-offs. A single 30-day late payment from five years ago is viewed differently than a recent 90-day delinquency. Underwriters assess whether you have stable employment history, reasonable debt levels relative to income, and sufficient reserves.
Debt-to-Income Ratio and Income Documentation
Your debt-to-income ratio (DTI) is a critical underwriting metric. It's calculated by dividing your total monthly debt obligations by your gross monthly income. Most lenders cap DTI at 43-50% for conventional mortgages, meaning your total monthly debt payments (including the new mortgage) cannot exceed 43-50% of your gross monthly income (consumerfinance.gov).
For example, if you earn $5,000 per month gross and your DTI limit is 43%, your total monthly debt payments can be at most $2,150. For self-employed borrowers or those with non-W2 income, underwriters typically average income over two years and may apply haircuts to account for variability.
Asset Verification and Reserve Requirements
Underwriters verify that your down payment funds are actually yours and not borrowed. They request bank statements showing the account history and confirm the funds have been seasoned (held in the account) for a specified period, typically 60 days. Many loan programs require borrowers to maintain reserves after closing, typically expressed as months of mortgage payment. For fix-and-flip investors, having adequate reserves demonstrates your ability to handle unexpected renovation costs or market shifts.
Loan-to-Value Ratio and Property Appraisal
The loan-to-value ratio (LTV) compares the loan amount to the property's appraised value. If you're borrowing $300,000 for a property appraised at $400,000, your LTV is 75%. Lower LTV ratios indicate lower risk because you have more equity cushion. Most conventional loans cap LTV at 80%.
The property appraisal is critical. An independent appraiser evaluates the property's market value based on comparable sales, property condition, and local market trends. If the appraisal comes in lower than the purchase price, you either need to negotiate a lower purchase price, increase your down payment, or walk away.
Mortgage Underwriting Timeline: What to Expect
A straightforward conventional loan with clean credit and standard W2 income typically takes 5-7 business days from application to clear-to-close, assuming you submit all required documents upfront (consumerfinance.gov). More complex scenarios take longer. A self-employed borrower with multiple income sources might need 10-14 days because the underwriter must analyze tax returns and business financials. The conditions phase adds 3-5 business days on average.
For investors using Kala Group Capital's platform, the process is accelerated. Credit decisions arrive in 30 seconds, preliminary term sheets in under 5 minutes, and funding can occur within days rather than the traditional 30-45 day timeline. This speed is particularly valuable for competitive bidding situations where you need to close quickly to secure the property.
Common Underwriting Red Flags That Delay Approval
Certain issues trigger underwriter concern and require additional investigation or documentation.
Large unexplained deposits in your bank statements raise questions. If a $50,000 deposit appears without explanation, the underwriter assumes it might be borrowed money. You'll need to provide a written explanation and documentation proving the source.
Employment gaps concern underwriters. If you were unemployed for three months, they want to know why and how you survived financially. A written explanation is typically sufficient, especially if the gap was recent and you've since found stable employment.
Recent large debts are problematic. If you took out a new car loan two months before applying for a mortgage, that new debt increases your DTI and may disqualify you.
Inconsistent income raises red flags. If your tax returns show declining income over the past two years, underwriters question whether your income is sustainable.
Credit score drops between pre-approval and underwriting signal potential problems. If your score dropped 50 points, underwriters investigate why.
Missing or incomplete documentation is the most common delay factor. Underwriters cannot approve without complete information.
DSCR Loan Underwriting Requirements
Debt Service Coverage Ratio (DSCR) loans are designed for real estate investors purchasing rental properties. Instead of evaluating personal income like a traditional mortgage, DSCR loans focus on the property's income-generating capacity.
The DSCR compares the property's annual net operating income (NOI) to the annual debt service (mortgage payments). A DSCR of 1.0 means the property's income exactly covers the mortgage payment. A DSCR of 1.25 means the property generates 25% more income than required for the mortgage payment. Most lenders require a minimum DSCR of 0.75 to 1.0 for investment properties (sba.gov).
DSCR underwriting requires different documentation than traditional mortgages. Instead of personal tax returns and W2s, underwriters request lease agreements, rent rolls, twelve months of property income and expense documentation, profit-and-loss statements, property management statements, and appraisals with income approach valuation. For investors using Kala Group Capital's DSCR loan products, this income-based approach is particularly valuable because it evaluates the property's performance rather than personal W2 income, making it ideal for experienced investors with diversified income sources.
Underwriting for Non-W2 Borrowers and Self-Employed Investors
Self-employed borrowers and those with non-W2 income face stricter underwriting scrutiny because their income is less predictable than W2 employees. Underwriters typically average self-employed income over two years using tax returns. Some lenders apply a haircut (reduction) to account for variability.
Documentation requirements include two years of personal tax returns, two years of business tax returns, current year profit-and-loss statements, business bank statements, personal bank statements, and explanations of any significant income changes. For investors managing multiple properties or complex income structures, working with a lender experienced in non-W2 underwriting is critical. Kala Group Capital specializes in financing experienced real estate investors, including those with self-employed and non-W2 income. The team understands how to properly document and present complex income scenarios to maximize your qualifying income and approval odds.
Post-Closing Quality Control
Underwriting doesn't end at closing. Many loan investors conduct post-closing quality control reviews to verify the loan was properly underwritten and documented. A quality control reviewer pulls the loan file and verifies that all required documents are present and properly executed, that the underwriter's decision was supported by documentation, that all conditions were satisfied before closing, and that the appraisal supports the loan amount.
This post-closing review typically happens 30-90 days after closing. If issues are discovered, the lender may be required to repurchase the loan from the investor. For borrowers, post-closing quality control is generally invisible, but understanding that this layer of review exists explains why lenders maintain strict underwriting standards.
Mortgage Underwriting Timeline Summary
| Phase | Typical Duration | What Happens | Key Factors |
|---|---|---|---|
| Application & Pre-Qualification | 1 day | Initial credit pull, basic qualification assessment | Speed depends on lender's systems |
| Document Submission | 3-5 days | Borrower gathers and submits documentation | Borrower responsiveness critical |
| Underwriting Review | 3-7 days | Underwriter analyzes documents, orders appraisal | Loan complexity affects duration |
| Conditions Phase | 3-5 days | Borrower satisfies conditions, provides explanations | Borrower speed is critical factor |
| Clear to Close | 2-3 days | Final review, title work, closing preparation | Typically fastest phase |
| Total Timeline | 5-25 days | From application to funding | Varies by complexity and responsiveness |
The mortgage underwriting process is thorough by design. Lenders are risking substantial capital, so they verify everything. For borrowers, understanding each phase and preparing documentation in advance significantly accelerates the timeline. For experienced real estate investors, working with a lender like Kala Group Capital that combines automated speed with human expertise in complex underwriting scenarios ensures you move from application to funding efficiently, keeping your investment timeline on track. Apply with Kala Group Capital and experience underwriting that respects your timeline while maintaining rigorous standards.
Frequently Asked Questions
How long does the real estate loan underwriting process typically take?
Underwriting duration varies based on loan complexity and document completeness. Standard loans often take 3-7 business days from submission to clear to close. Faster lenders using automated underwriting systems can provide initial credit decisions in minutes, though final approval depends on condition resolution. For experienced investors using specialized lenders like Kala Group Capital, the entire process from application to funding can occur within days when documentation is organized and ready upfront.
What are the most common reasons for loan denial during underwriting?
Underwriters deny loans based on creditworthiness concerns, insufficient income documentation, unacceptable debt-to-income ratios, property issues revealed in appraisal reports, or significant financial liabilities not disclosed. For non-W2 borrowers and self-employed investors, inconsistent tax returns or unexplained cash flow gaps frequently trigger denials. Pre-existing liens, title defects, or employment gaps also raise red flags. Addressing these issues before submission prevents delays and increases approval odds.
What should borrowers avoid doing while their loan is in underwriting?
Never open new credit accounts, make large purchases financed with debt, or change employment during underwriting. Avoid making unexplained deposits or transfers that affect bank statements and asset verification. Don't pay down existing debts significantly, as this raises questions about funds' origin. Refrain from co-signing other loans or changing your financial profile in any material way. These actions trigger additional scrutiny and conditions, delaying your clear to close status and funding timeline.
Does reaching the underwriting stage guarantee final loan approval?
No. Underwriting is where thorough risk assessment occurs. Many loans receive conditional approval, requiring additional documentation or explanations before clear to close status is granted. Some loans are denied outright if underwriting reveals unacceptable risk factors. However, reaching underwriting means your initial application and creditworthiness passed initial screening. Most conditional approvals are resolved within days if you respond promptly with requested documentation and explanations.
How does underwriting for DSCR loans differ from standard mortgage underwriting?
DSCR loan underwriting requirements focus on the property's income-generating potential rather than the borrower's personal income. Underwriters analyze debt service coverage ratio, rental income documentation, lease agreements, and property operating expenses. Personal credit scores matter less than property cash flow and the loan-to-value ratio. Tax returns for the property and profit-and-loss statements replace traditional employment verification. This makes DSCR loans attractive for real estate investment firms managing rental property portfolios seeking approval based on asset performance.
How does underwriting handle self-employed borrowers and non-W2 income?
Self-employed investors and non-W2 borrowers require additional income documentation beyond standard employment verification. Underwriters typically review 2 years of tax returns, business profit-and-loss statements, and bank statements showing consistent cash deposits. Some lenders use bank statement underwriting, which analyzes actual deposits rather than reported income. Specialized real estate lenders often have streamlined processes for self-employed investors managing multiple projects, recognizing that tax returns may not reflect actual cash flow. Organize documentation showing consistent income patterns to expedite underwriting.
What happens during the conditions phase of underwriting?
Conditional approval means the underwriter approves your loan pending resolution of specific items. Common conditions include clarifying unusual deposits, providing updated pay stubs, explaining credit inquiries, or addressing title issues. You receive a written list of conditions with deadlines. Respond with requested documentation promptly to avoid delays. The conditions phase typically takes 2-5 business days if materials are submitted quickly. Once all conditions are satisfied and verified, you receive clear to close status and proceed to funding.
What documents are required for real estate investment loan underwriting?
Standard documents include 2 years of tax returns, recent pay stubs or business profit-and-loss statements, 2 months of bank statements, employment verification, and a complete mortgage application. For investment properties, provide lease agreements, tenant information, and property operating expense documentation. You'll need a property appraisal report, title report, and homeowners insurance quote. Lenders may request asset verification showing reserves, investment account statements, and explanations for any financial liabilities. Having these organized before submission accelerates the underwriting process significantly.
This article was written using GrandRanker